
Introduction
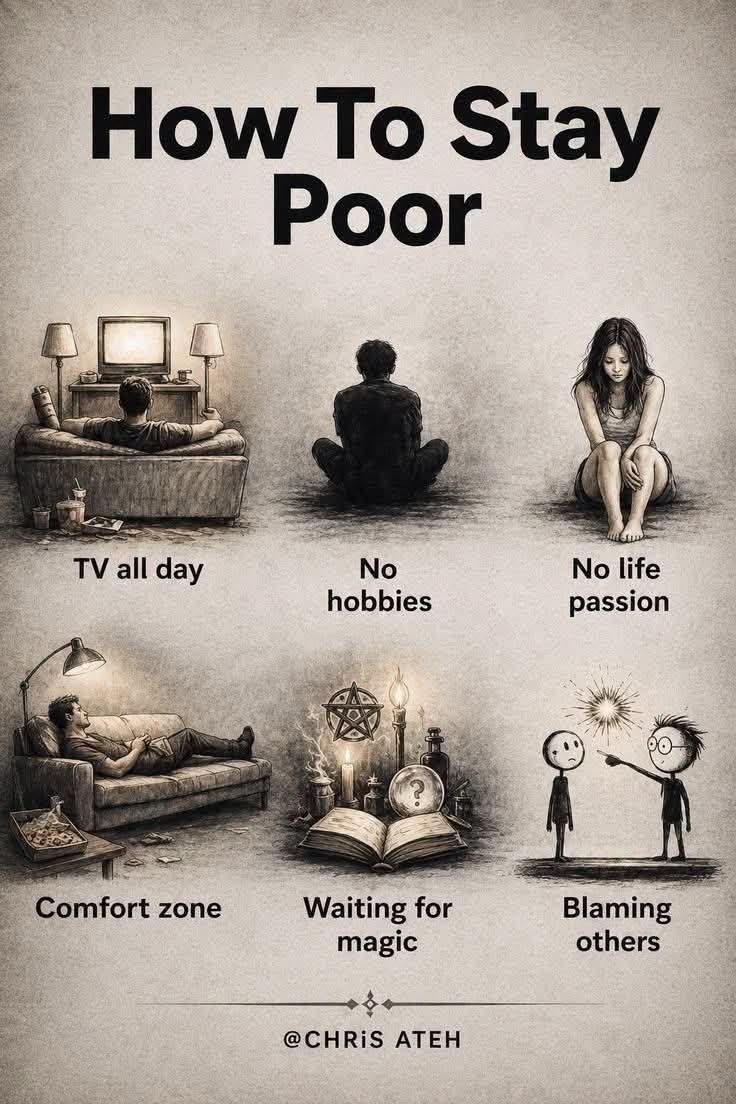
Achieving long-term financial security and building lasting wealth is rarely a matter of luck or overnight success. Instead, it is the direct result of consistent daily habits, mindset shifts, and intentional decision-making over time. Conversely, staying trapped in financial stagnation often stems from subtle, self-defeating behaviors that drain productivity and focus. A striking visual graphic titled “How To Stay Poor” outlines six pervasive lifestyle traps: watching TV all day, having no hobbies, lacking life passion, staying stuck in a comfort zone, waiting for magic, and constantly blaming others.
Understanding how these specific habits hinder personal growth and financial stability is the first step toward creating positive change. Just as individuals protect their tangible assets through prudent financial investments, obtaining health insurance, securing property loans, and consulting legal services, taking control of your daily habits safeguards your economic future. In this comprehensive guide, we will analyze the six psychological traps that sabotage wealth creation, explore actionable strategies to rebuild your mindset, share practical productivity tips, and answer key questions about achieving financial freedom.
The Six Behavioral Traps That Sabotage Financial Success
Recognizing negative behavior patterns allows individuals to replace passive consumption with intentional, value-generating habits.
Passive Consumption and the Comfort Zone
-
TV All Day and Passive Distraction: Spending hours consuming mindless entertainment depletes mental energy and steals valuable time that could be devoted to learning high-value skills or building income streams.
-
Staying in the Comfort Zone: Growth requires discomfort. Remaining strictly within your comfort zone prevents you from taking calculated risks, applying for new opportunities, or starting a business venture.
Lack of Passion and Purpose
-
No Hobbies and Creative Stagnation: Engaging in rewarding hobbies fosters creative problem-solving, stress relief, and networking opportunities that often lead to unexpected career advances.
-
No Life Passion: Living without clear personal or professional goals creates aimless drift, making it difficult to maintain the discipline needed for long-term financial growth.
Defeatist Mindsets: Magic vs. Personal Responsibility
-
Waiting for Magic: Hoping for an easy windfall, lottery win, or overnight miracle replaces structured financial planning and hard work with passive fantasy.
-
Blaming Others: Shifting responsibility onto external circumstances, employers, or luck destroys personal agency. Financial growth begins when you take full responsibility for your choices and actions.
Practical Steps to Transition from Stagnation to Wealth Building
Shifting away from unproductive habits requires establishing clear goals, building high-value skills, and practicing personal accountability:
-
Audit Your Daily Time Usage: Track how you spend your hours each day to identify passive distractions and replace television time with skill building or reading.
-
Set Clear Financial and Career Goals: Define specific, measurable financial targets—such as saving for investments, acquiring a certification, or launching a side project.
-
Embrace Daily Continuous Learning: Dedicate 30 to 60 minutes every day to reading industry books, taking online courses, or studying market trends.
-
Practice Extreme Personal Accountability: Stop placing blame on external circumstances. Focus entirely on the variables within your control, such as your work ethic, budget discipline, and skill set.
Fascinating Facts About Behavioral Psychology and Wealth
-
The Power of Compound Habits: In behavioral economics, small daily improvement habits compounding over years yield exponential improvements in professional performance and net worth.
-
The Locus of Control Concept: Psychologists categorize individuals as having either an “internal” or “external” locus of control; individuals with an internal locus believe their own actions determine their success, correlating directly with higher lifetime earnings.
-
Screen Time and Income Correlation: Demographic studies frequently demonstrate an inverse relationship between excessive non-work screen time and household savings rates.
Conclusion
Escaping financial stagnation is not about chasing quick shortcuts or waiting for luck. By recognizing destructive habits like passive consumption, comfort zone complacency, and external blame, you can consciously choose a path of purpose, continuous learning, and self-reliance. Taking full control of your daily routines today lays the groundwork for financial security, independence, and personal fulfillment tomorrow.
FAQ Section
How do daily habits impact long-term financial status?
Daily habits dictate how you allocate time, energy, and money. Prioritizing learning and disciplined saving builds equity over time, whereas passive entertainment and impulse spending erode financial stability.
What is the fastest way to get out of a comfort zone?
Start by taking small, low-risk steps outside your routine—such as learning a new technical skill, attending networking events, or setting ambitious weekly personal targets.
How does taking personal accountability improve financial success?
Taking accountability shifts your focus toward solutions and personal control, empowering you to improve skills, adjust budgets, and seek better career or business opportunities.
